Smart Water Meters Market Outlook: AMI Connectivity, Non-Revenue Water Reduction, Deployment Economics, and Digital Utility Services
Smart Water Meters Market: 6 Decisions Companies Should Make to Reduce Water Losses, Improve Metering Economics, and Scale Digital Water Infrastructure
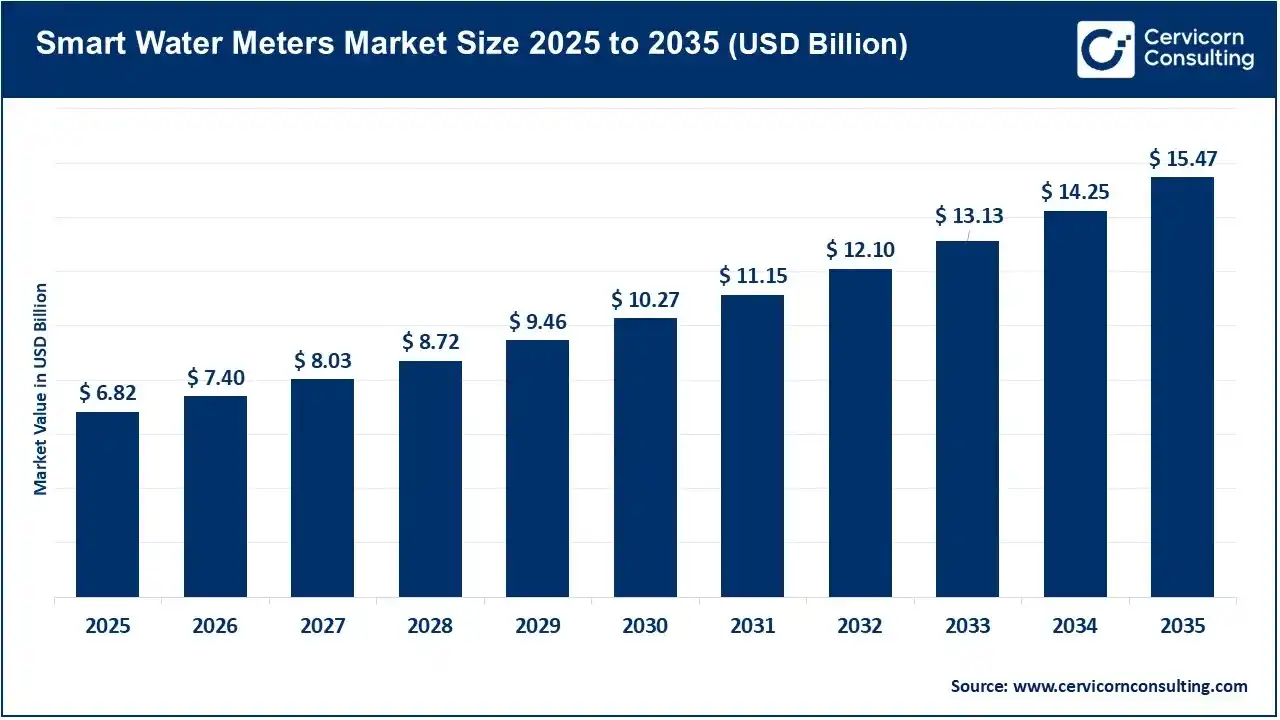
The global smart water meters market was valued at USD 6.82 billion in 2025 and is projected to reach approximately USD 15.47 billion by 2035, growing at a compound annual growth rate (CAGR) of 8.6% from 2026 to 2035. The market is being shaped by rising water stress, aging distribution infrastructure, the need to reduce non-revenue water, and the transition from manual meter reading toward connected monitoring and data-driven utility operations.
For water utilities, meter manufacturers, technology providers, and infrastructure investors, the commercial opportunity extends beyond replacing conventional meters. The critical question is how to translate connected measurement into measurable improvements in billing accuracy, leak detection, operational efficiency, and customer service.
However, the economics of smart water metering depend on several interrelated decisions. Meter selection, communication infrastructure, software integration, deployment strategy, and service models determine whether a project delivers sustainable operational value or creates another layer of technology expenditure.
1. Should Companies Prioritize Meter Replacement or Broader Water Network Modernization?
Smart water meter deployments often begin with replacing conventional meters, but replacement alone does not guarantee meaningful reductions in water losses. Companies must determine whether their primary objective is to improve measurement accuracy, reduce manual reading costs, detect abnormal consumption, or strengthen network-wide water management.
In 2025, mechanical smart water meters equipped with digital modules accounted for approximately 42% of the global market revenue, reflecting the opportunity to modernize existing metering infrastructure without replacing every mechanical device. Ultrasonic meters accounted for approximately 32%, offering an alternative for applications where measurement precision, low-flow detection, and reduced mechanical wear are important.
The appropriate investment depends on the condition of the installed meter base, expected service life, water quality, flow characteristics, and the cost of integrating new devices with existing systems.
Key decisions companies should make:
- Assess whether existing mechanical meters can be upgraded with communication modules or require complete replacement.
- Compare ultrasonic, electromagnetic, and digitally enabled mechanical meters against application-specific accuracy and lifecycle requirements.
- Prioritize installations in locations where inaccurate measurement, frequent maintenance, or unexplained consumption creates the greatest financial impact.
- Evaluate whether meter deployment should be coordinated with pipe rehabilitation, pressure monitoring, and district metered area management.
Business implication: Manufacturers that offer flexible modernization pathways can address both cost-sensitive replacement projects and advanced digital infrastructure programs. Utilities should prioritize measurable operational improvements rather than the number of meters installed.
Get a Free Sample: https://www.cervicornconsulting.com/sample/3074
2. Should Companies Invest in AMR or Advanced Metering Infrastructure?
The choice between Automatic Meter Reading (AMR) and Advanced Metering Infrastructure (AMI) affects project cost, data availability, maintenance requirements, and long-term operational capabilities.
AMR automates the collection of meter readings, reducing manual fieldwork and supporting more efficient billing. Depending on the configuration, readings may be collected through walk-by, drive-by, or fixed-network systems. AMI generally provides a more comprehensive architecture with two-way communications, enabling more frequent data collection, remote configuration, and additional monitoring functions.
In 2025, AMR represented approximately 35% of the smart water meters market revenue. AMI accounted for approximately 28% and offers opportunities for utilities seeking more advanced monitoring and control capabilities.
Neither approach is universally superior. Utilities with limited budgets and straightforward billing requirements may find AMR sufficient. Organizations managing complex distribution networks, high water losses, or extensive customer bases may benefit more from the capabilities of AMI.
Key decisions companies should make:
- Compare the total cost of ownership of AMR and AMI over the intended operating period.
- Determine whether daily or periodic readings are sufficient or whether more frequent data is necessary for leak detection and operational response.
- Assess whether two-way communications justify additional hardware, connectivity, and software expenditure.
- Identify future requirements for remote diagnostics, customer alerts, demand forecasting, and integration with utility management systems.
Business implication: AMI can create opportunities for recurring software, analytics, and connectivity revenue, while AMR remains relevant for cost-conscious modernization. Technology providers should align their offerings with the operational maturity and investment capacity of each utility.
3. Which Communication Technology Offers the Best Deployment Economics?
Communication infrastructure is a critical factor in smart water meter performance. A meter may accurately measure consumption but still deliver limited value if readings cannot be transmitted reliably or the communication network is expensive to maintain.
Smart water metering projects use several connectivity options, including cellular communication, radio frequency (RF), and low-power wide-area network (LPWAN) technologies. The appropriate solution depends on geographic coverage, installation density, underground chamber conditions, data transmission frequency, and network ownership costs.
Cellular connectivity can reduce the need for utilities to construct and maintain their own communications networks, although recurring connectivity charges and coverage limitations must be considered. RF and LPWAN solutions can be attractive for large, geographically concentrated deployments, provided sufficient network coverage and dependable data collection can be achieved.
Key decisions companies should make:
- Evaluate communication reliability across underground meter chambers, dense urban districts, industrial sites, and remote locations.
- Compare network construction costs, recurring data charges, gateway requirements, and expected maintenance expenditure.
- Test interoperability with existing utility infrastructure before committing to a large-scale rollout.
- Consider whether open standards and multi-vendor compatibility can reduce supplier dependence over the project’s lifecycle.
Business implication: Companies offering reliable, interoperable communication solutions can differentiate themselves beyond meter hardware. Utilities should assess connectivity as a lifecycle investment rather than selecting a technology solely on its initial price.
4. How Can Smart Water Metering Deliver Measurable Reductions in Non-Revenue Water?
Non-revenue water refers to water that enters a distribution system but does not generate revenue, including losses from leakage, unauthorized consumption, and metering or billing inaccuracies. Smart meters can improve visibility into consumption and help utilities investigate unexplained differences between water supplied and water billed.
However, customer-level smart meters cannot independently identify every leak in a distribution network. Realizing their full value requires combining consumption information with district-level flow measurements, pressure sensors, geographic information systems, and appropriate analytical tools.
Utilities must therefore determine how metering data will trigger operational action. An alert has limited value if maintenance teams cannot validate the problem, locate its source, and respond within a commercially meaningful timeframe.
Key decisions companies should make:
- Establish baseline measurements for water losses, billing discrepancies, meter inaccuracies, and leak response times.
- Integrate customer meter data with network flow and pressure information where appropriate.
- Use consumption anomalies to prioritize inspections and distinguish potential customer-side leaks from wider distribution problems.
- Track the financial value of recovered water, avoided field visits, improved collections, and reduced investigation costs.
- Establish performance indicators before deployment so improvements can be measured against the original operating baseline.
Business implication: The strongest value proposition for analytics providers is not simply generating alerts; it is helping utilities prioritize interventions and verify outcomes. Performance-based contracts may become attractive where suppliers and utilities can agree on reliable measurement and attribution methods.
5. How Should Companies Structure Procurement, Financing, and Deployment?
Large-scale smart water meter projects require coordinated investment in devices, installation, communications, data platforms, integration, and ongoing maintenance. For utilities with constrained budgets, these combined costs can make a technically attractive project difficult to approve.
A deployment strategy based solely on the lowest meter price may overlook installation complexity, battery life, communication failures, replacement requirements, and software integration expenses. Conversely, a comprehensive AMI rollout may be difficult to justify if the utility lacks the operational capacity to use the additional data.
Companies should build an investment case around total cost of ownership and clearly defined operational outcomes.
Key decisions companies should make:
- Compare phased deployment, full-network replacement, and targeted installation in high-loss or high-consumption areas.
- Calculate lifecycle costs covering procurement, installation, communications, software, maintenance, battery replacement, and eventual device replacement.
- Evaluate conventional procurement alongside leasing, managed-service arrangements, and performance-based commercial models where available.
- Define measurable service-level agreements for data availability, device reliability, installation quality, and maintenance response.
- Assess local manufacturing, supply-chain resilience, and service coverage when selecting vendors for large or geographically dispersed projects.
Business implication: Vendors that can demonstrate reliable implementation, predictable lifecycle costs, and measurable utility benefits may be better positioned in competitive procurement processes. Financing and service models can also expand access to customers unable to fund complete deployments upfront.
6. How Can Companies Turn Metering Data into Recurring Revenue and Competitive Advantage?
Smart water metering is evolving from a hardware-focused business into a connected service ecosystem. Meters generate the data, but the long-term value increasingly depends on how effectively that information supports billing, asset management, customer engagement, predictive maintenance, and water conservation.
For manufacturers, utilities, and software providers, this creates an opportunity to develop offerings that extend beyond the initial equipment sale. Examples include meter-data management platforms, leak detection analytics, remote diagnostics, customer consumption portals, and managed monitoring services.
The commercial opportunity nevertheless depends on the quality of the data, compatibility with existing systems, customer willingness to pay, and the ability to demonstrate operational improvements.
Key decisions companies should make:
- Determine whether to sell standalone meters, integrated AMI solutions, software subscriptions, or managed metering services.
- Develop application-specific analytics for residential utilities, commercial buildings, industrial facilities, and municipal networks.
- Establish cybersecurity, access-control, data-retention, and privacy requirements for connected deployments.
- Build partnerships with utility software providers, system integrators, communications companies, and infrastructure contractors.
- Measure customer retention, recurring revenue, implementation costs, and demonstrable customer savings before scaling new service offerings.
Business implication: Integrated solutions can create longer customer relationships and recurring revenue opportunities. Companies that connect hardware performance with useful operational insights may be better positioned to differentiate themselves in an increasingly competitive market.
What Should Companies Prioritize in the Smart Water Meters Market?
The smart water meters market is expanding, but growth alone does not determine which investments will produce attractive returns. The commercial opportunity depends on matching technology, deployment strategy, and service delivery to specific utility challenges.
For water utilities, the priority should be to establish a measurable business case around water-loss reduction, billing performance, maintenance costs, and customer service. For meter manufacturers, competitive positioning will depend on lifecycle reliability, communication flexibility, integration capabilities, and the ability to serve different budget levels. For software and technology providers, the opportunity lies in turning consumption data into actionable operational improvements.
Before committing to a major investment, companies should evaluate three priorities:
- Operational value: Identify the water-loss, billing, maintenance, or customer-service problem the project is expected to solve.
- Deployment economics: Compare meter technologies, communication networks, implementation models, and lifecycle costs.
- Long-term scalability: Ensure the selected architecture can support future analytics, interoperability, cybersecurity, and service requirements.
The next phase of market development will favor solutions that demonstrate measurable value across the full metering lifecycle. Companies that connect procurement decisions with operational outcomes will be better equipped to evaluate investment opportunities, develop differentiated offerings, and compete for large-scale water infrastructure projects.
To Get Detailed Overview, Contact Us: https://www.cervicornconsulting.com/contact-us