India Diagnostics Services Market Outlook: Geographic Expansion, Diagnostic Portfolio Optimization, Profitability, and Operational Efficiency
India Diagnostics Services Market: 6 Strategic Decisions Companies Should Make to Improve Profitability, Expand Access, and Strengthen Competitive Positioning
India’s diagnostics services market is entering a new phase of growth, shaped by rising demand for preventive healthcare, increasing chronic disease prevalence, expansion into smaller cities, and growing adoption of specialized testing. For diagnostic laboratory operators, hospital groups, imaging providers, and healthcare investors, the central challenge is no longer simply whether demand will increase. It is how to capture that demand while maintaining testing quality, controlling operating costs, and generating sustainable returns on investment.
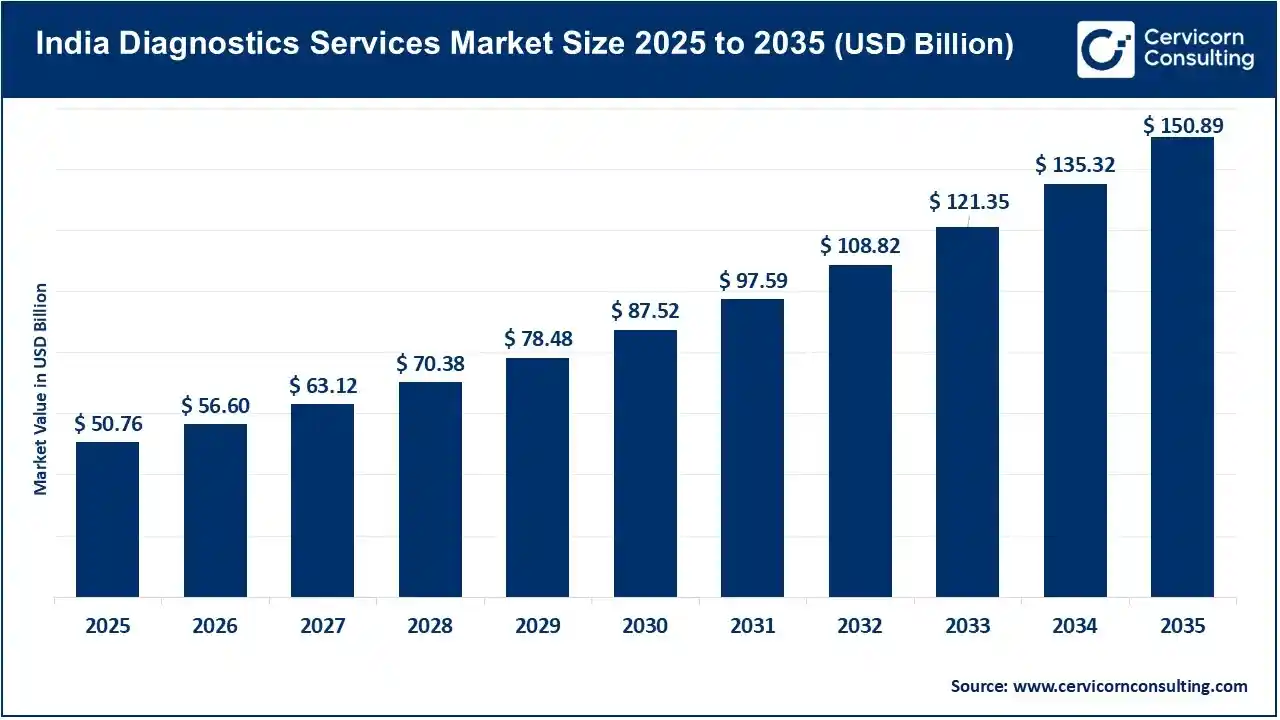
The India diagnostics services market was valued at USD 50.76 billion in 2025 and is projected to reach USD 150.89 billion by 2035, expanding at a compound annual growth rate (CAGR) of 11.5% from 2026 to 2035. Pathology testing accounted for 52% of market revenue in 2025, while independent diagnostic laboratories represented 35% of the market by service provider. These figures indicate the importance of routine testing volumes and the continued role of independent operators in India’s fragmented diagnostics ecosystem.
However, market growth does not automatically translate into higher profitability. Companies must make deliberate decisions about where to expand, which tests to prioritize, how to price services, and when to invest in advanced diagnostic capabilities.
1. Should Companies Prioritize Tier-2 and Tier-3 Cities or Strengthen Their Existing Urban Networks?
Geographic expansion is one of the most important strategic decisions for diagnostic service providers. Metropolitan markets offer established referral networks, higher concentrations of specialists, and access to patients seeking advanced testing. At the same time, competition between diagnostic chains, hospital laboratories, and independent providers can place pressure on prices and customer acquisition costs.
Smaller cities offer a different opportunity. Rising healthcare awareness, expanding medical infrastructure, and demand for accessible testing are encouraging diagnostic companies to extend their networks beyond major urban centers. Business Standard reported in December 2024 that diagnostic demand in Tier-2 and Tier-3 towns was growing rapidly, with industry participants identifying these markets as important expansion opportunities.
Nevertheless, entering a smaller city without sufficient patient volumes or referral relationships can result in underutilized laboratories, inefficient sample transportation, and longer investment payback periods.
Key decisions for companies:
- Map local demand before opening facilities: Assess population density, disease burden, hospital infrastructure, physician concentration, competitor presence, and existing diagnostic capacity.
- Select the appropriate operating model: Consider a collection center linked to a central laboratory, a regional processing hub, a franchise facility, or a fully equipped standalone laboratory.
- Evaluate sample logistics: Estimate collection volumes, transport frequency, sample stability requirements, and turnaround-time commitments before establishing a new service location.
- Prioritize underserved catchments: Identify locations where patients face long travel distances or limited access to reliable testing rather than entering markets solely because competitors are expanding there.
Business implication: A phased hub-and-spoke strategy can help companies expand access without duplicating expensive laboratory infrastructure in every location. The most attractive market is not necessarily the city with the largest population, but the one where achievable test volumes, referral access, and operating costs support sustainable returns.
Get a Free Sample: https://www.cervicornconsulting.com/sample/3072
2. Which Diagnostic Services Should Companies Prioritize for Growth?
Diagnostic providers must decide how to balance high-volume routine tests with specialized services that may offer different revenue and margin opportunities.
Pathology testing remains a central part of the Indian diagnostics business because tests such as complete blood counts, glucose testing, lipid profiles, and liver and kidney function assessments support routine healthcare and chronic disease monitoring. Cervicorn Consulting estimates that pathology testing accounted for 52% of the India diagnostics services market in 2025.
However, growth opportunities extend beyond routine pathology. Molecular and genomic diagnostics can support infectious disease detection, oncology, inherited disease testing, and treatment selection. Preventive and wellness testing also creates opportunities to develop recurring patient relationships, provided that packages are clinically appropriate and priced transparently.
Investing in every available testing category is rarely the best approach. Advanced testing may require expensive equipment, specialist personnel, quality-control systems, and sufficient sample volumes to justify in-house processing.
Key decisions for companies:
- Protect the economics of routine testing: Improve analyzer utilization, reagent procurement, laboratory workflow, and quality control across high-volume tests.
- Identify specialized tests with unmet local demand: Evaluate molecular diagnostics, oncology testing, microbiology, and other specialized services against regional disease patterns and referral demand.
- Compare in-house processing with outsourcing: Determine whether specialized tests should be performed internally or referred to a reference laboratory based on expected volumes, turnaround times, and total costs.
- Build preventive testing around patient needs: Develop relevant screening and monitoring packages instead of relying exclusively on broad discounts or large test bundles.
- Assess test-level profitability: Track revenue per test, consumable costs, repeat-testing rates, quality failures, and contribution margins.
Business implication: A portfolio built around reliable routine testing, supported by carefully selected specialized services, can improve customer retention and diversify revenue. The investment decision should be based on expected local demand and achievable utilization rather than technology adoption alone.
3. How Should Diagnostic Providers Compete on Price Without Eroding Margins?
Price competition is a persistent challenge in India’s diagnostics industry. Independent laboratories, national chains, hospital-based facilities, and digital diagnostic platforms often compete for overlapping patient groups. Discounts, bundled health packages, promotional campaigns, and home sample collection can attract customers, but they may also reduce profitability when acquisition and delivery costs are not properly measured.
Pricing also varies by geography and service category. A CRISIL industry analysis reproduced in a SEBI-hosted document indicates that pathology test prices in Tier-2 and Tier-3 cities are generally 20–30% lower than in Tier-1 cities, while radiology test prices are typically 2–12% lower. These are indicative industry comparisons, not universal price differences across all providers or tests.
This makes a uniform national pricing strategy difficult to sustain. Companies need to understand the relationship between local purchasing power, competitor pricing, service quality, and the cost of delivering each test.
Key decisions for companies:
- Calculate the true cost per test: Include reagents, consumables, personnel, equipment depreciation, quality assurance, collection, transportation, and reporting.
- Establish location-specific pricing: Account for local competition, patient affordability, test volumes, and service complexity.
- Measure the profitability of discounted packages: Evaluate whether promotional pricing generates incremental customers or merely reduces revenue from patients who would have paid the regular price.
- Differentiate on reliability and convenience: Compete through dependable turnaround times, accurate reporting, accessible locations, and effective communication rather than price alone.
- Monitor customer and channel economics: Compare the contribution generated by walk-in patients, physician referrals, institutional contracts, home collection, and online aggregators.
Business implication: The objective should be to maximize sustainable contribution rather than test volumes alone. Discounting may be appropriate for selected services or customer segments, but it should be supported by clear utilization, retention, and profitability targets.
4. Should Companies Invest in Advanced Imaging, Molecular Diagnostics, and Genomic Testing?
Technological investment can help diagnostic providers expand their service portfolios and improve clinical capabilities. Yet the financial and operational requirements vary substantially across technologies.
Advanced imaging equipment such as CT and MRI systems can require significant upfront capital, maintenance expenditure, facility preparation, and access to qualified radiologists. Molecular and genomic testing may require specialized laboratory infrastructure, validated workflows, trained personnel, and reliable quality-control processes.
The strategic question is not whether advanced diagnostics will become more important. It is whether a particular provider can generate sufficient demand to justify the investment.
Key decisions for companies:
- Estimate realistic utilization: Forecast monthly test volumes using local referral demand, disease incidence, competitor capacity, and the provider’s expected market share.
- Compare purchasing with partnership models: Evaluate equipment ownership against hospital partnerships, managed-service arrangements, equipment leasing, or referral agreements.
- Assess the complete cost of ownership: Include maintenance contracts, upgrades, consumables, staffing, downtime, and the cost of financing.
- Select technologies that fit the existing network: Providers with established laboratory volumes may be better positioned to add selected molecular tests than operators without sufficient infrastructure or specialist expertise.
- Validate clinical and commercial requirements: Confirm applicable regulatory requirements, quality standards, reporting responsibilities, and reimbursement or patient-payment arrangements.
Business implication: Advanced technology is most valuable when it addresses a clear clinical need and has a credible path to utilization. Partnership or referral models may be more economical than direct ownership when local volumes are uncertain.
5. How Can Companies Build a Scalable Home Collection and Digital Diagnostics Model?
Home sample collection and digital reporting can improve convenience, particularly for elderly patients, individuals managing chronic conditions, and customers who have difficulty visiting a laboratory. Digital channels can also simplify booking, payment, report delivery, and communication with referring healthcare professionals.
However, convenience does not guarantee attractive unit economics. Collection routes can become expensive when bookings are geographically dispersed, appointment volumes are unpredictable, or samples require time-sensitive handling. Customer acquisition costs can also rise when providers rely heavily on paid digital marketing or aggregator platforms.
Key decisions for companies:
- Define viable service areas: Prioritize neighborhoods and localities where expected booking density supports efficient collection routes.
- Optimize collection scheduling: Group appointments geographically and establish service windows that balance convenience with transport and sample-stability requirements.
- Integrate digital systems: Connect bookings, laboratory information systems, sample tracking, reporting, and customer support to minimize manual work and errors.
- Monitor service-level performance: Track collection punctuality, sample rejection rates, report turnaround times, complaint resolution, and repeat bookings.
- Develop recurring relationships: Support chronic disease monitoring and clinically appropriate preventive testing through convenient follow-up services.
Business implication: Home collection should be managed as an operational network, not simply an additional sales channel. Companies that combine digital access with efficient route planning and dependable laboratory operations can improve convenience without allowing fulfillment costs to overwhelm margins.
6. Should Companies Expand Independently, Form Partnerships, or Pursue Acquisitions?
India’s diagnostics sector remains fragmented, with independent laboratories, organized diagnostic chains, and hospital-based laboratories serving different patient segments. Fragmentation creates opportunities for geographic expansion, network partnerships, acquisitions, and consolidation. It also makes competitive positioning more complex.
For established chains, acquisitions can provide immediate access to local customers, referral relationships, and operating facilities. For independent laboratories, partnerships with larger networks may offer access to specialized tests, centralized processing, technology, and broader distribution.
However, an acquisition does not automatically create value. Differences in laboratory quality, reporting systems, pricing, staffing, and customer relationships can complicate integration. Similarly, a partnership may fail to deliver expected returns if responsibilities, service standards, and commercial terms are not clearly defined.
Key decisions for companies:
- Identify capability gaps: Determine whether the next phase of growth requires geographic access, specialized testing, stronger referral networks, improved technology, or greater processing capacity.
- Compare expansion options: Evaluate the capital requirements, speed to market, operating risks, and expected returns of building, partnering, franchising, or acquiring.
- Conduct operational due diligence: Review test volumes, customer concentration, equipment condition, quality-control records, staff retention, regulatory compliance, and financial performance.
- Set integration priorities: Standardize reporting, quality assurance, procurement, information systems, and service-level expectations before aggressively expanding the combined network.
- Establish measurable investment criteria: Track return on invested capital, utilization, revenue growth, cash generation, customer retention, and payback periods.
Business implication: The best growth model depends on the company’s existing capabilities and target market. Acquisitions can accelerate expansion where integration is manageable, while partnerships and hub-and-spoke networks may provide a more capital-efficient route into underserved locations.
Conclusion: Growth Will Depend on Better Capital Allocation and Execution
India’s diagnostics services market presents opportunities across routine pathology, preventive screening, advanced imaging, molecular diagnostics, and digitally enabled service delivery. With the market projected by Cervicorn Consulting to increase from USD 50.76 billion in 2025 to USD 150.89 billion by 2035, companies have a substantial growth opportunity. However, capturing that growth will require more than adding facilities or increasing test volumes.
The most important strategic priorities are to select locations with viable demand, build a balanced testing portfolio, protect margins through disciplined pricing, invest in technology according to utilization requirements, improve home collection economics, and choose the right expansion model.
For diagnostic chains, these decisions can guide geographic expansion and network optimization. For independent laboratories, they can help identify profitable specialization and partnership opportunities. For hospital groups and investors, they provide a framework for evaluating capacity requirements, competitive positioning, and the long-term economics of diagnostic service delivery.
Ultimately, the strongest diagnostic businesses will be those that convert rising demand into reliable service quality, efficient operations, and sustainable financial returns.
To Get Detailed Overview, Contact Us: https://www.cervicornconsulting.com/contact-us