Power MOSFET Market Outlook: Semiconductor Technology Selection, Power Efficiency, Application Prioritization, and Supply Chain Resilience
Power MOSFET Market: 6 Decisions Companies Should Make to Improve Power Efficiency, Reduce Design Costs, and Strengthen Technology Positioning
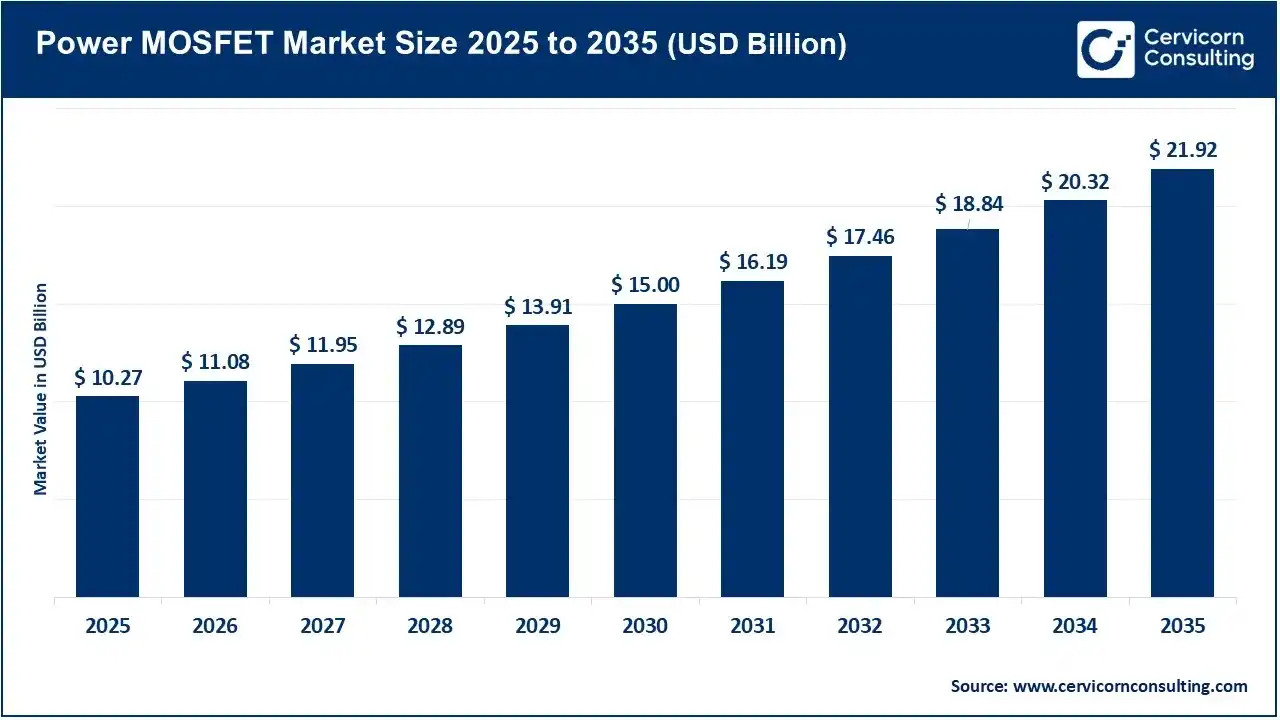
The global power MOSFET market was valued at USD 10.27 billion in 2025 and is projected to reach approximately USD 21.92 billion by 2035, growing at a compound annual growth rate (CAGR) of 7.8% from 2026 to 2035. Growth is being supported by electric vehicle adoption, industrial automation, renewable energy installations, high-density computing infrastructure, and rising demand for efficient power conversion.
However, market growth alone does not guarantee commercial success for semiconductor manufacturers and power-electronics companies. Product selection is becoming more application-specific as manufacturers balance switching performance, conduction losses, thermal requirements, component costs, qualification timelines, and supply-chain reliability. Silicon MOSFETs continue to serve cost-sensitive applications, while silicon carbide (SiC) and gallium nitride (GaN) technologies are gaining attention in designs where higher efficiency, faster switching, or greater power density can justify additional investment.
For manufacturers, the central question is not simply which technology will grow fastest. It is where each technology can deliver measurable system-level value, which customer segments offer the strongest commercial opportunities, and how product portfolios should evolve without creating unnecessary cost or development risk.
1. Which Power MOSFET Technology Should Companies Prioritize?
Selecting the right semiconductor material is becoming a strategic decision for companies developing automotive electronics, industrial power supplies, charging equipment, and energy infrastructure. Silicon, SiC, and GaN each offer different performance and cost advantages, making a single-technology strategy unsuitable for many manufacturers.
Silicon MOSFETs remain competitive in established applications where manufacturing scale, cost efficiency, and proven reliability are important. They are widely used in consumer electronics, low-voltage power management, switching power supplies, and numerous industrial systems. SiC MOSFETs are attractive for higher-voltage applications where reduced switching and conduction losses, thermal performance, and high-power conversion can improve overall system economics. GaN devices are particularly relevant to high-frequency power conversion, compact chargers, and selected data-center power architectures.
Companies should assess these technologies against actual operating conditions rather than relying solely on headline efficiency claims.
Key decisions for companies:
- Retain silicon for applications where cost, availability, and established qualification outweigh the benefits of newer materials.
- Evaluate SiC for high-voltage power conversion, electric vehicle powertrains, charging systems, and renewable energy inverters.
- Assess GaN where high switching frequency, compact form factors, and power density are important design requirements.
- Compare total system cost, including gate drivers, cooling, passive components, packaging, and qualification—not just the semiconductor’s purchase price.
Business implication: A segmented technology roadmap can help companies protect established product margins while selectively investing in higher-performance devices. The priority should be identifying applications where technology differentiation translates into customer value and a defensible commercial advantage.
Get a Free Sample: https://www.cervicornconsulting.com/sample/3071
2. Which End-Use Markets Offer the Strongest Commercial Opportunities?
Power MOSFET demand spans consumer electronics, automotive and electric vehicles, data centers and telecommunications, industrial equipment, and renewable energy systems. These markets differ considerably in purchase volumes, qualification requirements, pricing pressure, and product lifecycles.
According to the market estimates, consumer electronics accounted for approximately 24% of global power MOSFET market revenue in 2025, while automotive and electric vehicles represented around 25%. Data centers and telecommunications contributed approximately 18%, industrial equipment 20%, and renewable energy and power supplies 13%.
These figures illustrate why companies should evaluate opportunities beyond total market size. Consumer electronics can offer substantial volumes but often involve intense price competition and short product cycles. Automotive applications may require lengthy qualification and rigorous reliability validation, but successful design wins can support longer supply relationships. Industrial customers may prioritize operating reliability, service life, and compatibility with existing equipment. Data-center operators place considerable emphasis on power efficiency, thermal management, and power density.
Key decisions for companies:
- Prioritize customer segments according to expected demand, achievable margins, qualification costs, and sales-cycle length.
- Assess automotive opportunities in onboard chargers, auxiliary power conversion, battery systems, and electric power distribution.
- Evaluate data-center applications involving server power supplies, high-efficiency conversion, and emerging rack-power architectures.
- Identify industrial and renewable energy customers seeking lower operating losses, improved reliability, and reduced cooling requirements.
Business implication: Companies should develop separate commercial strategies for high-volume, price-sensitive markets and specialized applications where performance, reliability, and engineering support can justify premium pricing.
3. How Should Companies Allocate Investment Across Voltage Ratings?
Voltage rating influences device architecture, manufacturing requirements, performance characteristics, and target applications. The market’s requirements extend from low-voltage switching in portable electronics to higher-voltage devices used in automotive systems, industrial power conversion, and renewable energy infrastructure.
In 2025, low-voltage power MOSFETs accounted for approximately 51% of market revenue, followed by medium-voltage devices at 30% and high-voltage devices at 19%. The market outlook indicates a gradual shift toward higher-voltage applications, supported by electrification, charging infrastructure, and increasing power-conversion requirements.
However, this does not mean manufacturers should automatically redirect investment away from low-voltage products. Low-voltage devices remain important in computing, consumer electronics, battery management, and auxiliary automotive systems. Medium- and high-voltage opportunities require more specific assessment of end-use demand, device performance, packaging, and qualification requirements.
Key decisions for companies:
- Maintain competitive low-voltage portfolios where production scale and cost optimization remain decisive.
- Identify medium-voltage opportunities in industrial power supplies, motor control, automotive auxiliary systems, and charging equipment.
- Evaluate high-voltage device development against demand for electric vehicle powertrains, renewable energy conversion, and other demanding applications.
- Match voltage capability with switching frequency, current requirements, thermal limits, and expected operating conditions.
Business implication: Voltage-based investment should follow identifiable customer programs and application requirements. This approach can help manufacturers avoid overinvestment in technically advanced products without sufficient near-term demand.
4. How Can Companies Improve Efficiency Without Increasing Total System Cost?
Efficiency improvements are commercially valuable when they reduce energy losses, simplify thermal management, improve equipment performance, or lower lifetime operating costs. Yet the most efficient semiconductor is not always the most economical choice for every system.
Power MOSFET performance depends on several interacting characteristics, including on-resistance, gate charge, switching losses, output capacitance, thermal resistance, and package design. Optimizing one parameter in isolation can create trade-offs elsewhere. For example, reducing conduction losses may affect switching performance, while faster switching can increase electromagnetic interference and place additional demands on circuit design.
These considerations are particularly important in high-density server power supplies, automotive converters, industrial drives, and renewable energy systems, where small changes in power losses can influence cooling requirements and system-level efficiency.
Key decisions for companies:
- Compare conduction and switching losses under realistic operating conditions rather than relying exclusively on datasheet maximum ratings.
- Evaluate thermal performance at the complete system level, including package resistance, cooling design, and operating temperature.
- Assess whether a higher-cost device can reduce the need for cooling hardware, passive components, or other system-level expenditures.
- Validate performance across load ranges and operating cycles to understand efficiency under actual customer conditions.
Business implication: Companies that connect semiconductor specifications to measurable system-level savings can make stronger product-positioning decisions. This also provides a clearer basis for explaining premium pricing to customers focused on lifecycle costs rather than component price alone.
5. How Should Companies Reduce Supply-Chain and Qualification Risks?
Power MOSFET manufacturers operate within a supply chain influenced by wafer availability, fabrication capacity, packaging and testing capabilities, raw material costs, regional manufacturing concentration, and changing customer demand. These risks can become particularly important for automotive and industrial customers that require consistent device performance and long-term availability.
Supply-chain resilience also requires more than identifying a second supplier. Devices from different manufacturers may have different electrical characteristics, footprints, thermal behavior, and qualification status. Substitution can therefore require additional engineering work and testing before a product can be released.
Companies expanding into SiC and GaN must also consider technology-specific manufacturing capabilities, packaging requirements, supplier maturity, and the availability of qualified alternatives.
Key decisions for companies:
- Identify critical devices with concentrated sourcing, extended lead times, or limited qualified alternatives.
- Evaluate suppliers using reliability history, manufacturing capabilities, quality systems, technical support, and long-term product availability.
- Develop second-source strategies for components whose disruption could delay production or customer deliveries.
- Assess whether alternative devices can be adopted without substantial redesign, testing, or regulatory requalification.
- Align inventory policies with demand variability, component lead times, and the commercial cost of production interruptions.
Business implication: A structured supplier-risk strategy can improve production continuity and reduce the financial exposure associated with component shortages. For manufacturers serving automotive and industrial customers, supply reliability can also become a competitive differentiator.
6. Which Capabilities Should Companies Build to Strengthen Their Competitive Position?
As power MOSFET technologies evolve, competition increasingly depends on the combination of device performance, packaging, application engineering, manufacturing economics, and customer support. Companies must determine whether to compete through scale and cost efficiency, differentiated device technology, specialized application knowledge, or a combination of these capabilities.
Established manufacturers may benefit from broad portfolios and mature production networks, while specialized suppliers can focus on particular voltage ranges, package formats, or demanding end markets. In either case, investment decisions should reflect identifiable customer requirements and the company’s ability to commercialize new technology.
The expansion of SiC and GaN creates opportunities, but developing a new device family involves more than achieving favorable electrical characteristics. Companies must also address production yields, reliability validation, thermal design, application compatibility, and customer qualification.
Key decisions for companies:
- Determine whether competitive advantage will come primarily from cost, performance, packaging, reliability, or application-specific design.
- Prioritize research and development around customer problems that existing products do not adequately solve.
- Strengthen application engineering and technical support to help customers optimize complete power-conversion systems.
- Evaluate partnerships with packaging specialists, equipment manufacturers, and system integrators where they can shorten development cycles.
- Track competitor product launches, qualification wins, capacity investments, and portfolio changes to identify gaps in the market.
Business implication: A focused product roadmap can help companies allocate R&D resources more effectively and avoid spreading investment across too many technologies or applications. Competitive differentiation is most sustainable when device capabilities address a clearly defined customer requirement.
What Should Companies Prioritize in the Power MOSFET Market?
The power MOSFET market’s projected growth creates opportunities across established silicon applications and emerging SiC- and GaN-enabled systems. However, commercial outcomes will depend on how effectively companies align technology investment with customer requirements, manufacturing capabilities, cost targets, and supply-chain resilience.
Three priorities stand out:
- Technology alignment: Select silicon, SiC, and GaN according to application-specific performance and cost requirements rather than treating one technology as a universal replacement for another.
- Application selection: Focus resources on customer segments that offer an appropriate balance of addressable demand, profitability, qualification effort, and long-term growth.
- Execution discipline: Connect product development, supplier strategy, and engineering investment to measurable customer needs and system-level performance improvements.
Companies that evaluate these decisions together will be better positioned to identify commercially viable opportunities, protect margins, and adapt their product portfolios as power-electronics requirements evolve.
The key strategic question is not simply how quickly the Power MOSFET Market will expand, but which applications, technologies, and customer relationships can create sustainable value for each business.
To Get Detailed Overview, Contact Us: https://www.cervicornconsulting.com/contact-us