Biometrics Payment Market: Strategic Priorities for Secure, Scalable and Frictionless Digital Transactions
Biometrics Payment Market Size and Growth Outlook
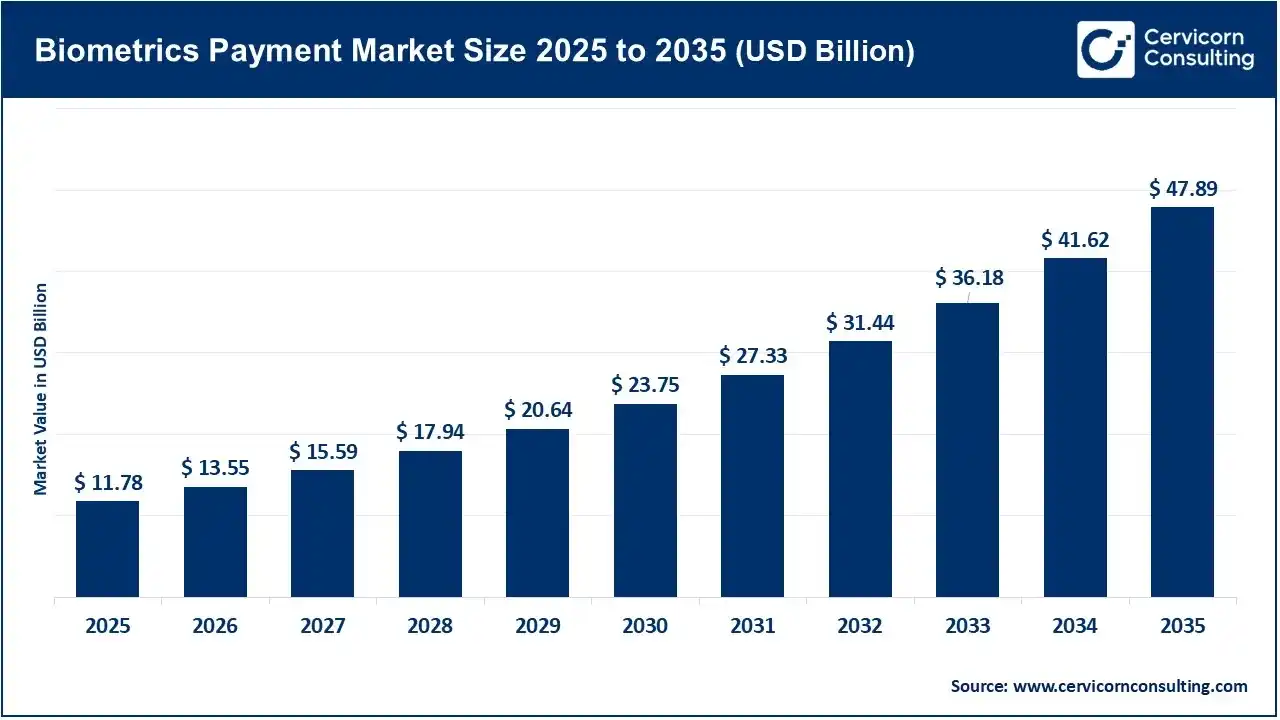
The global biometrics payment market was valued at USD 11.78 billion in 2025 and is projected to reach approximately USD 47.89 billion by 2035, expanding at a CAGR of 15% from 2026 to 2035. The market is benefiting from increasing payment fraud, growing contactless transaction volumes, smartphone-based authentication, and the demand for faster and more secure payment experiences.
Biometric payment technologies use unique physical or behavioral characteristics, including fingerprints, facial features, iris patterns, palm prints, vein patterns, and voice recognition, to authenticate financial transactions. These technologies are increasingly being integrated into smartphones, payment cards, point-of-sale (POS) terminals, banking applications, and online payment platforms.
In 2025, fingerprint recognition accounted for 45% of the market, while facial recognition represented 28%. Hardware held the largest component share at 42%, and banking and financial institutions represented 35% of end-user demand. North America led the global market with a 34% revenue share.
However, market expansion does not automatically translate into commercial success for every technology provider. Payment networks, financial institutions, fintech companies, retailers, and biometric technology vendors must evaluate where biometric authentication can deliver measurable improvements in transaction security, customer experience, operating efficiency, and long-term profitability.
The following strategic priorities examine the decisions businesses should consider when investing in or expanding biometric payment solutions.
1. Which Biometric Authentication Technology Should Companies Prioritize?
Selecting the right biometric modality is one of the most important decisions for companies entering the biometrics payment market. Different authentication technologies offer varying levels of accuracy, convenience, infrastructure requirements, deployment costs, and consumer acceptance.
Fingerprint recognition currently holds the largest market share, supported by its integration into smartphones, biometric payment cards, and POS authentication systems. Its established infrastructure and familiarity among consumers make it a practical option for financial institutions and payment service providers seeking broader adoption.
Facial recognition is gaining attention because it supports contactless transactions and can be integrated into existing smartphone cameras and specialized payment terminals. Its potential is particularly relevant for retailers, hospitality businesses, and mobile payment platforms seeking faster customer authentication.
Palm and vein recognition offer another opportunity, particularly in environments where touch-free authentication and resistance to certain forms of physical imitation are important. Iris and voice recognition may also serve specialized payment environments, although their commercial suitability depends on deployment conditions and customer acceptance.
Business considerations:
- Evaluate authentication accuracy, false acceptance rates, and false rejection rates across different customer groups.
- Compare hardware requirements and integration costs for fingerprint, facial, palm, and other recognition technologies.
- Assess liveness detection and protection against spoofing, presentation attacks, and identity manipulation.
- Determine whether a single biometric modality is sufficient or whether multimodal authentication is necessary for higher-risk transactions.
- Evaluate consumer familiarity and accessibility before selecting a technology for large-scale deployment.
Strategic implication: Companies should avoid selecting biometric technologies solely because they are growing quickly. The right investment should reflect transaction risk, customer demographics, deployment environments, and the total cost of implementation.
Get a Free Sample: https://www.cervicornconsulting.com/sample/3077
2. How Should Payment Providers Balance Security With Transaction Convenience?
One of the primary commercial opportunities in biometric payments is reducing authentication friction without compromising transaction security.
Traditional payment authentication methods, including passwords, PINs, and one-time passwords, can create additional steps during checkout. Biometric authentication offers an alternative by enabling customers to authorize transactions through device-level fingerprint or facial recognition.
However, faster authentication should not become a reason to weaken fraud prevention. Payment providers must consider account takeover attempts, synthetic identities, spoofing, unauthorized device access, and other evolving fraud techniques.
Companies should establish authentication policies based on transaction value, customer behavior, payment location, device integrity, and the level of potential financial exposure.
For example, a familiar low-value transaction on a trusted device may require a different authentication process from an unusually large payment initiated from an unfamiliar device.
Business considerations:
- Introduce risk-based authentication instead of applying identical verification requirements to every transaction.
- Combine biometric verification with device intelligence, transaction monitoring, and behavioral analytics.
- Evaluate whether biometric authentication can reduce checkout abandonment and payment-related friction.
- Establish additional verification requirements for high-value or unusual transactions.
- Monitor authentication performance through fraud losses, false rejection rates, transaction completion rates, and customer complaints.
Strategic implication: Payment providers should measure biometric authentication through both security outcomes and transaction performance. A solution that reduces checkout time but increases fraud exposure may not deliver sustainable commercial value.
3. Should Companies Invest in Biometric Hardware or Software-Led Payment Infrastructure?
The market’s component structure presents an important investment decision for payment technology companies.
Hardware accounted for 42% of the biometrics payment market in 2025, reflecting the importance of sensors, biometric readers, payment terminals, and secure devices. Software represented 35%, while services accounted for 23%.
Hardware investment is relevant for companies manufacturing biometric payment cards, POS terminals, fingerprint sensors, palm scanners, and other authentication devices. However, large-scale deployment can involve substantial equipment expenditure, installation requirements, maintenance, and compatibility challenges.
Software-led solutions offer a different growth opportunity. Biometric authentication algorithms, identity verification platforms, fraud detection applications, and authentication management systems can be integrated into existing payment ecosystems. This may allow technology providers to expand their customer base without depending entirely on physical infrastructure deployment.
Services also provide commercial opportunities through system integration, implementation support, cybersecurity assessments, compliance management, and ongoing infrastructure maintenance.
Business considerations:
- Compare the economics of proprietary biometric hardware with software integration into existing devices.
- Assess the availability of compatible POS terminals, smartphones, payment cards, and secure elements.
- Evaluate recurring revenue opportunities through authentication software, licensing, and maintenance services.
- Determine whether partnerships with payment networks or terminal manufacturers can reduce deployment costs.
- Examine the long-term costs of device upgrades, software updates, and cybersecurity maintenance.
Strategic implication: Companies should evaluate their position across the hardware, software, and services value chain rather than assuming that the largest component segment offers the most attractive investment opportunity. Software and services may offer different scalability and recurring-revenue advantages.
4. How Can Companies Address Biometric Data Privacy and Regulatory Compliance?
Privacy and data protection remain major considerations for biometric payment adoption. Unlike passwords or PINs, biometric characteristics cannot easily be replaced if compromised. Unauthorized access to biometric information can therefore create long-term identity and security risks.
Financial institutions and payment technology providers must evaluate how biometric information is collected, processed, stored, transmitted, and protected throughout the payment lifecycle.
The choice between on-device authentication and centralized biometric processing is particularly important. On-device authentication can reduce the need to transfer sensitive biometric information across networks, while centralized systems may introduce additional data governance, storage, and security requirements.
Companies operating across multiple countries must also consider differences in data protection regulations, consent requirements, biometric information processing, and financial transaction security standards.
Business considerations:
- Assess applicable requirements under regulations such as GDPR and relevant national data protection frameworks.
- Evaluate encrypted biometric templates, secure storage, and controlled access mechanisms.
- Consider on-device processing to minimize unnecessary transmission of sensitive biometric information.
- Establish transparent customer consent, retention, deletion, and data access policies.
- Conduct regular security testing, vulnerability assessments, and third-party technology audits.
- Evaluate regulatory and legal responsibilities across payment networks, financial institutions, merchants, and technology vendors.
Strategic implication: Privacy and regulatory compliance should be incorporated during product development rather than addressed after commercialization. Companies that establish strong data governance practices can reduce deployment risks and improve customer confidence.
5. Which Payment Channels Offer the Strongest Commercial Opportunities?
Biometric payment adoption is expanding across in-store payments, online transactions, mobile payments, ATM services, and transportation-related payment systems. However, the commercial requirements and adoption barriers differ across these channels.
In-store payments accounted for 30% of the market in 2025, supported by biometric POS terminals, contactless checkout systems, and growing interest in faster retail transactions.
Online payments represent an important growth opportunity as businesses seek alternatives to conventional passwords and OTP-based authentication. Device-level biometrics and passkeys can support secure customer verification while reducing unnecessary checkout steps.
Mobile payments are also gaining importance because smartphones increasingly function as authentication devices, digital wallets, and transaction management platforms.
For companies evaluating market entry or expansion, channel selection should depend on infrastructure readiness, transaction frequency, customer behavior, and integration requirements.
Business considerations:
- Retailers should evaluate whether biometric checkout can reduce queues and improve transaction completion rates.
- Banks should assess biometric authentication for mobile banking, ATM access, and card-based transactions.
- E-commerce companies should examine the integration of device biometrics and passkeys into checkout processes.
- Payment technology providers should prioritize APIs and platforms compatible with different wallets, payment networks, and merchant systems.
- Transportation operators should evaluate biometric payment applications where high transaction volumes and rapid passenger movement make authentication efficiency important.
Strategic implication: Companies should prioritize payment channels where biometric authentication addresses a clearly identifiable operational or customer problem. Expanding across every payment channel simultaneously can increase integration complexity and capital requirements.
6. Where Should Companies Focus Their Regional Expansion Strategies?
Regional expansion requires an understanding of differences in digital payment infrastructure, smartphone penetration, consumer trust, regulatory frameworks, and financial service adoption.
North America accounted for 34% of the global biometrics payment market in 2025, with an estimated market value of USD 4.01 billion. Its established banking ecosystem, payment networks, retail infrastructure, and growing adoption of digital authentication support its leading position.
Asia-Pacific was valued at approximately USD 3.53 billion in 2025 and is expected to reach USD 14.37 billion by 2035. Its growth potential is supported by smartphone adoption, digital payment ecosystems, super-apps, and the expansion of technology-enabled financial services.
India represents an important market to monitor because of its large digital payments ecosystem and growing interest in biometric authentication for financial transactions. However, companies must evaluate local payment infrastructure, regulatory requirements, consumer accessibility, and the commercial viability of different authentication models before committing to large-scale investments.
Europe also presents opportunities, particularly as digital identity frameworks, payment authentication requirements, and data protection considerations influence the development of biometric payment infrastructure.
Business considerations:
- Prioritize regions with established digital payment infrastructure and suitable biometric-enabled devices.
- Evaluate regional privacy requirements and financial authentication standards before entering new markets.
- Assess the role of local banks, payment networks, fintech companies, and technology integrators.
- Compare customer adoption patterns and willingness to use biometric payment methods.
- Identify opportunities for partnerships with domestic payment service providers and retail technology companies.
Strategic implication: Regional expansion should be based on infrastructure readiness and commercial adoption potential rather than population size or digital payment transaction volumes alone.
7. Which Partnerships Can Accelerate Commercialization and Market Adoption?
Biometric payment systems require coordination among multiple stakeholders, including biometric technology developers, payment networks, banks, fintech companies, device manufacturers, POS providers, and cybersecurity vendors.
For many companies, building an entire biometric payment ecosystem internally may increase development time, infrastructure expenditure, and commercialization risks.
Strategic partnerships can help businesses access established payment infrastructure, authentication technology, distribution networks, and customer relationships.
For example, biometric technology developers can collaborate with payment networks to integrate authentication into existing card and wallet ecosystems. POS manufacturers can work with facial or palm recognition providers to develop integrated checkout systems. Banks and fintech companies can partner with authentication software providers to improve digital transaction security.
However, partnership decisions should be evaluated based on technical compatibility, intellectual property ownership, data governance responsibilities, service-level requirements, and long-term commercial arrangements.
Business considerations:
- Identify payment networks and financial institutions with active biometric authentication initiatives.
- Evaluate technology licensing, integration partnerships, and joint product development opportunities.
- Assess interoperability with existing payment terminals, digital wallets, and banking platforms.
- Establish clear responsibilities for customer data protection, fraud liability, and system maintenance.
- Evaluate partner capabilities in regional distribution, regulatory compliance, and technical support.
Strategic implication: Companies should build partnerships around complementary capabilities rather than simply expanding the number of technology integrations. A well-structured ecosystem can reduce time to market and improve commercialization prospects.
Competitive Landscape: Companies Shaping the Biometrics Payment Market
Competition in the biometrics payment market involves payment networks, biometric hardware manufacturers, authentication technology providers, identity management companies, and financial technology platforms.
Key companies include:
Mastercard Incorporated and Visa Inc.
Mastercard and Visa play an important role in connecting biometric authentication with existing card payment and digital payment ecosystems. Their competitive positioning is supported by payment network infrastructure, tokenization capabilities, issuer relationships, and authentication technologies. Their strategic focus includes integrating stronger customer verification into established payment experiences.
Thales Group
Thales operates across digital identity, cybersecurity, and secure transaction technologies. Its capabilities in identity verification, authentication, and secure payment infrastructure position it to serve financial institutions and payment technology providers seeking integrated security solutions.
IDEMIA Group
IDEMIA specializes in identity technologies, biometric authentication, and secure payment solutions. Its activities across biometric payment cards, digital identity, and authentication infrastructure provide opportunities to participate in the shift toward more secure payment experiences.
Fingerprint Cards AB
Fingerprint Cards focuses on fingerprint biometric technology, including sensors and biometric solutions for payment cards and connected devices. Its market opportunities are closely associated with the adoption of fingerprint-enabled payment cards and secure authentication applications.
NEC Corporation
NEC provides biometric identification and authentication technologies, including facial recognition. Its experience in identity management and enterprise security creates opportunities in financial services, payment authentication, and digital identity applications.
IDEX Biometrics ASA
IDEX Biometrics focuses on fingerprint authentication technologies and biometric payment card solutions. Its positioning is particularly relevant to financial institutions and card manufacturers exploring card-based biometric authentication.
ZKTeco Co., Ltd.
ZKTeco operates in biometric identification, access control, and security hardware. Its capabilities in biometric devices and authentication systems provide potential applications across payment terminals and integrated commercial environments.
Dermalog Identification Systems GmbH
Dermalog develops biometric identification technologies, including fingerprint and facial recognition solutions. Its expertise in identity verification and biometric systems supports opportunities in secure financial transactions and authentication infrastructure.
J.P. Morgan Payments
J.P. Morgan Payments operates across payment processing, treasury services, and financial transaction infrastructure. Its banking and payment capabilities provide a foundation for integrating advanced authentication technologies into enterprise and financial payment services.
Signzy
Signzy focuses on digital identity verification, onboarding, and financial technology solutions. Its capabilities in identity verification and automation are relevant to financial institutions seeking stronger customer authentication and fraud prevention.
Minkasu
Minkasu provides payment authentication and checkout-related technology solutions. Its activities are relevant to businesses evaluating secure and friction-reducing authentication experiences across digital payment environments.
Conclusion: Turning Biometric Payment Adoption Into a Sustainable Business Opportunity
The biometrics payment market is moving beyond smartphone-based fingerprint authentication toward a broader ecosystem involving biometric payment cards, facial recognition, palm authentication, digital wallets, secure POS terminals, and software-based identity verification.
With the global market projected to reach USD 47.89 billion by 2035, opportunities exist across biometric hardware, authentication software, payment processing, cybersecurity, and system integration.
However, long-term commercial success will depend on more than technology adoption. Companies must establish the right balance between authentication security, customer convenience, data privacy, infrastructure costs, and regulatory compliance.
Financial institutions should prioritize fraud reduction and secure customer authentication. Retailers should evaluate checkout efficiency and customer acceptance. Technology providers should assess the scalability of their hardware and software offerings. Payment networks should focus on interoperability, partnerships, and consistent authentication experiences across different transaction environments.
The companies best positioned to benefit will be those that connect biometric innovation with measurable business outcomes and sustainable payment infrastructure.
To Get Detailed Overview, Contact Us: https://www.cervicornconsulting.com/contact-us