


Buy Now Pay Later Market: Growth Opportunities Depend on Credit Risk, Merchant Economics and Regulatory Readiness
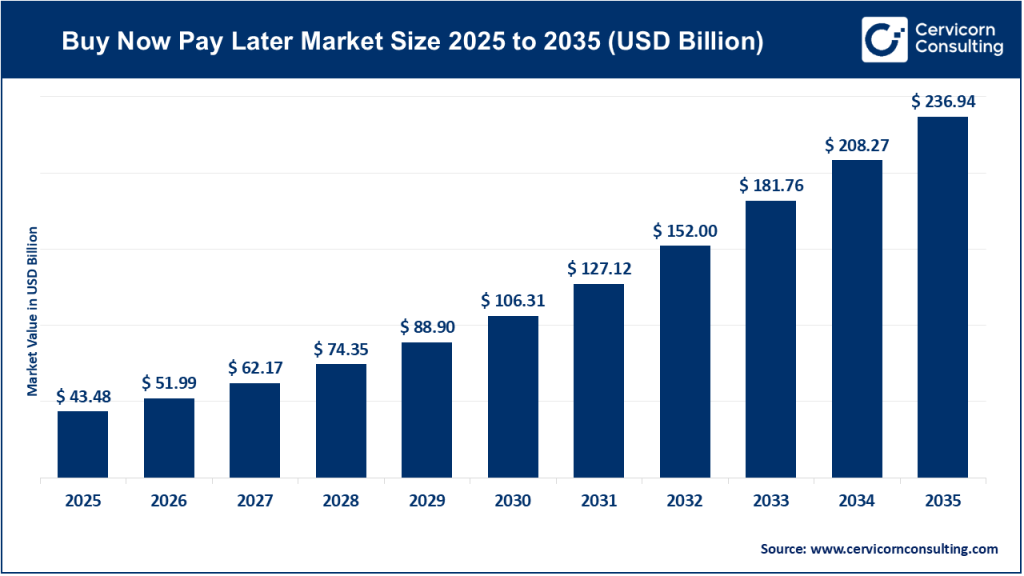
The global buy now pay later (BNPL) market was valued at USD 43.48 billion in 2025 and is projected to reach approximately USD 236.94 billion by 2035, expanding at a CAGR of 18.48% from 2026 to 2035. The market is benefiting from increasing digital payments, changing consumer purchasing behaviour, e-commerce expansion, and demand for flexible financing options.
However, the next phase of BNPL growth will depend on more than transaction volumes and merchant adoption. Providers must balance customer acquisition with repayment performance, funding costs, fraud prevention, and regulatory compliance. Merchants must also evaluate whether installment-based payments generate incremental sales or simply shift customers from existing payment methods.
As BNPL expands beyond traditional retail into travel, healthcare, education, and other service categories, companies face important decisions regarding product design, customer eligibility, merchant partnerships, and geographic expansion.
1. Merchant Adoption Must Be Evaluated Against Actual Transaction Economics
BNPL has become an increasingly important checkout option for online retailers and merchants seeking to improve purchasing flexibility. In 2025, the retail segment accounted for 69% of the global BNPL market, while point-of-sale transactions represented 84.30% of the market.
For merchants, offering installment payments can improve checkout conversion, increase average order values, and reduce cart abandonment. However, these benefits must be compared against merchant discount rates, transaction fees, refund costs, and integration expenses.
Companies should evaluate:
-
Whether BNPL attracts genuinely incremental customers or shifts existing credit card transactions.
-
How installment options influence average order value and repeat purchases.
-
Whether merchant fees are justified by higher conversion rates and contribution margins.
-
Which product categories generate the strongest repayment and transaction performance.
Business implication: Merchants should prioritize BNPL partnerships based on incremental revenue and profitability rather than transaction growth alone.
Get a Free Sample: https://www.cervicornconsulting.com/sample/2413
2. Credit Risk Assessment Will Determine Long-Term Provider Profitability
BNPL providers face a fundamental challenge: approving customers quickly while maintaining sustainable repayment performance.
Unlike conventional lending, BNPL often operates through simplified checkout experiences and rapid credit decisions. However, expanding customer acquisition without sufficiently assessing repayment capacity can increase delinquency, fraud exposure, and credit losses.
Artificial intelligence, machine learning, alternative data, and real-time transaction analytics are creating opportunities to improve underwriting processes.
Providers should focus on:
-
Developing credit assessment models using transaction history and repayment behaviour.
-
Identifying customers with multiple outstanding installment obligations.
-
Improving fraud detection through behavioural analytics and identity verification.
-
Adjusting credit limits based on customer repayment performance.
-
Monitoring delinquency across customer groups, merchants, and product categories.
The Federal Reserve’s June 2026 analysis estimated that major BNPL providers originated approximately USD 160 billion in consumer credit products during 2025, highlighting the scale of financing activity beyond traditional pay-in-four products.
federalreserve.gov
Business implication: BNPL providers should prioritize risk-adjusted lending growth instead of maximizing approval rates and transaction volumes.
3. Regulatory Readiness Is Becoming a Competitive Requirement
Regulatory developments are changing how BNPL providers structure lending arrangements, disclose repayment obligations, and manage customer protection.
In India, the Reserve Bank of India’s Digital Lending Directions, 2025 introduced consolidated requirements covering lender partnerships, borrower creditworthiness, disclosures, loan disbursement, repayment, data usage, and grievance redressal.
Reserve Bank of India+1
Similarly, the UK Financial Conduct Authority brought third-party deferred payment credit arrangements under its regulation from 15 July 2026. The framework includes affordability assessments, clearer customer disclosures, and additional consumer protections.
FCA+1
For BNPL companies operating across multiple markets, regulatory differences can influence operating costs, partnership structures, product eligibility, and expansion timelines.
Companies should assess:
-
Licensing and regulatory requirements in target markets.
-
Affordability assessment and responsible lending obligations.
-
Disclosure requirements covering repayment schedules, fees, and missed payments.
-
Data privacy, cybersecurity, and third-party technology arrangements.
-
Complaint management and customer protection procedures.
Business implication: Regulatory compliance should be incorporated into market-entry planning and product development rather than treated as a post-expansion requirement.
4. Geographic Expansion Requires Market-Specific Business Models
Regional demand for BNPL is influenced by digital payment infrastructure, consumer credit penetration, e-commerce maturity, regulatory frameworks, and merchant acceptance.
In 2025, North America accounted for 32.80% of global BNPL market revenue, while Asia-Pacific represented 28.70%. Both regions offer significant opportunities, but their competitive and operating environments differ.
North America benefits from established BNPL providers, developed digital commerce infrastructure, and strong merchant partnerships. Asia-Pacific offers opportunities through expanding e-commerce ecosystems, mobile payment adoption, and demand for alternative financing solutions.
For companies evaluating geographic expansion, important considerations include:
-
Local consumer purchasing behaviour and preferred installment structures.
-
Availability of banking and lending partnerships.
-
Credit bureau coverage and alternative credit assessment capabilities.
-
Regulatory requirements and consumer protection standards.
-
Merchant acquisition costs and competitive intensity.
Business implication: Providers should prioritize markets where payment infrastructure, credit availability, merchant demand, and regulatory conditions support sustainable operations.
5. Expansion Beyond Retail Creates Opportunities but Requires Different Risk Models
Although retail remains the largest application area, BNPL providers are increasingly exploring travel, healthcare, and education.
These categories present different transaction characteristics and customer repayment requirements.
For example, travel financing involves seasonal demand, cancellations, and refund management. Healthcare financing requires consideration of treatment costs, provider partnerships, and customer affordability. Education financing may involve larger ticket sizes and longer repayment periods.
Companies entering these markets should evaluate:
-
Average transaction values and repayment periods.
-
Merchant settlement and refund arrangements.
-
Customer acquisition costs and repayment capacity.
-
Demand consistency and seasonal transaction patterns.
-
Industry-specific compliance and partnership requirements.
Business implication: Diversification can reduce dependence on retail transactions, but each application requires a suitable underwriting, pricing, and partnership strategy.
6. Funding Partnerships and Operational Scalability Will Shape Competitive Positioning
BNPL providers require sustainable funding sources to support growing transaction volumes and manage liquidity requirements.
Merchant fees, lending partnerships, institutional funding, and other financing arrangements influence the economics of BNPL operations.
Partnerships with banks and private credit firms can provide access to capital, lending infrastructure, and broader customer networks. However, providers must assess the cost of capital, funding concentration, credit exposure, and contractual dependencies.
Technology investments are equally important. Automated underwriting, payment processing, fraud detection, and collections infrastructure can help providers manage larger customer bases without proportionately increasing operating expenses.
Companies should evaluate:
-
Cost and availability of institutional funding.
-
Dependence on individual banking or capital partners.
-
Loan portfolio performance and funding concentration.
-
Technology infrastructure and transaction processing capacity.
-
Collections efficiency and operational cost per transaction.
Business implication: Competitive advantage will increasingly depend on the ability to scale lending operations while maintaining healthy unit economics and funding stability.
Market Outlook: What Companies Should Prioritize
The BNPL market is transitioning from a checkout convenience into a broader consumer financing ecosystem. Growth opportunities are emerging across retail, travel, healthcare, education, and other service categories, but competitive success will depend on how effectively companies manage credit exposure, merchant economics, and regulatory requirements.
For BNPL providers, the priority is to develop sustainable lending models supported by advanced risk assessment, diversified funding, and efficient operations. Merchants should focus on identifying customer segments and product categories where installment payments generate measurable commercial value.
Investors and financial institutions should monitor portfolio quality, funding arrangements, competitive positioning, and the ability of providers to operate profitably across different regulatory environments.
The next phase of BNPL competition will be determined not simply by who processes more transactions, but by who can convert transaction growth into sustainable financial performance.
To Get Detailed Overview, Contact Us: https://www.cervicornconsulting.com/contact-us